
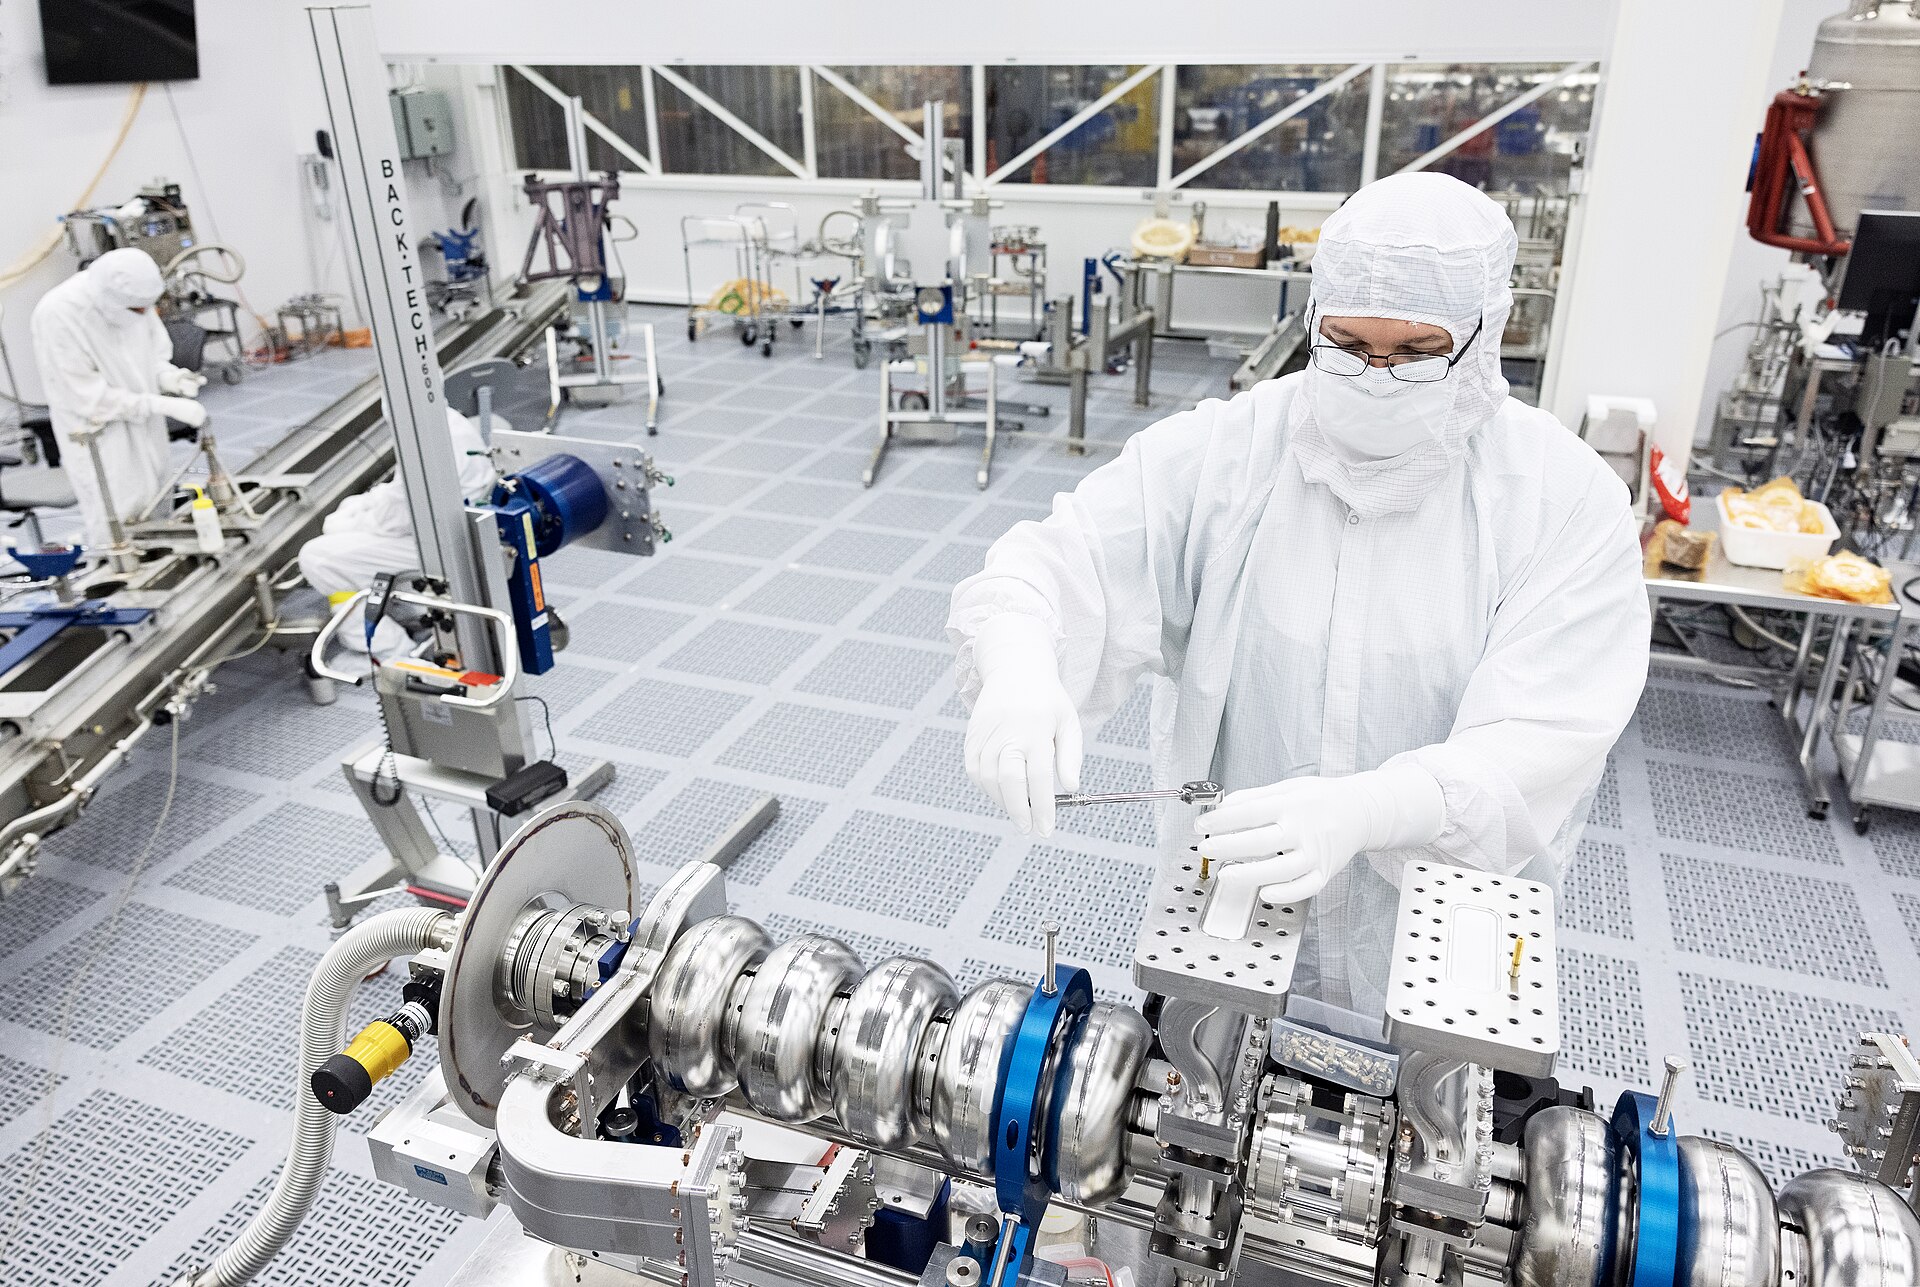
The most contested objects on Earth are smaller than a postage stamp. Advanced semiconductors power artificial intelligence, weapons systems, cars and the phones in our pockets, and the race to design and manufacture them has become the defining industrial contest of the decade. Governments that once treated chips as a commodity now treat them as strategic infrastructure, closer to oil fields than to ordinary electronics.
The numbers explain the urgency. A single leading-edge fabrication plant can cost more than twenty billion dollars and take years to build, yet demand from AI data centres keeps outrunning supply. Readers following our reporting will know how often the same names recur: a handful of firms design the most advanced processors, one company dominates the machines that print them, and one island fabricates most of the world’s cutting-edge supply.
That concentration is precisely what worries policymakers. Export controls, subsidies and tariffs now swirl around the industry, and each new announcement — a factory in Arizona, a packaging plant in Europe, a research hub in Japan — is read as a move on a geopolitical chessboard as much as a business decision.
How the Supply Chain Became So Concentrated
Semiconductor manufacturing rewards scale and punishing precision. Making chips at the smallest geometries requires extreme ultraviolet lithography machines that only the Dutch firm ASML produces, optics from a small circle of suppliers, and process knowledge accumulated over decades. Analysis by Reuters’ technology team has repeatedly shown how this web of specialisation makes the supply chain brilliant and brittle at the same time: extraordinarily efficient, but exposed at a few narrow points.
Design has concentrated too. The AI boom elevated the designers of graphics processors and custom accelerators, while the foundry model — one company manufacturing chips for hundreds of clients — rewarded the firm that executed best. Rebuilding that ecosystem elsewhere is not impossible, but it is slow, because the bottleneck is often not money; it is the small global pool of engineers who know how to run these processes at yield.
Subsidies, Controls and the New Industrial Policy
The United States, the European Union, Japan, South Korea and India have all launched subsidy programmes measured in tens of billions, an embrace of industrial policy that would have been unthinkable a generation ago. At the same time, export controls restrict the flow of the most advanced chips and tools to strategic rivals. Our technology section follows these policy moves closely, because they now shape product roadmaps as surely as any engineering breakthrough.
Critics warn that duplication is wasteful and that controls accelerate the very self-sufficiency they aim to slow. Supporters reply that resilience is worth a premium when a single disruption — a pandemic, an earthquake, a blockade — could idle car plants and hospitals worldwide. Both arguments can be true at once, which is why the race looks less like a sprint with a finish line and more like a permanent condition of the technology economy.
What the Race Means Beyond the Factory Gates
For businesses, the chip race shows up as allocation lists, longer lead times and pressure to design products around whatever silicon is actually available. For consumers, it appears in the price and capability of everything from laptops to electric cars. The AI services that dominate headlines run on these chips, so the pace of the race quietly sets the pace of the software revolution built on top of it.
The next contest is already visible: advanced packaging, which stacks and links chips together, and new materials that promise efficiency beyond today’s transistors. The BBC’s business coverage has tracked how investment is spreading into those niches. Whoever leads them will not just sell components; they will hold a lever over the industries of the next thirty years. That is why governments are no longer willing to leave the outcome to the market alone.
